How Small Businesses Should Actually Set Up AI Fraud Detection in 2026
Sift, SEON and Trustpair compared for small businesses, plus the built-in options in Stripe Radar and Shopify, with a rollout plan that needs no fraud analyst.
 Stanislav VovchykSep 3, 202613 min readUpdated Nov 1, 2026
On this page · 11 sections
- 1. Why Rule-Based Systems Are Losing Ground
- 2. Which Fraud Problem Are You Solving?
- 3. Comparison Table
- 4. Trustpair: Purpose-Built for Vendor Fraud
- 5. Sift: Built for E-Commerce Fraud
- 6. SEON: The Accessible Option
- 7. The SMB-Native Defaults: Stripe Radar and Shopify
- 8. What a Small Business Needs From Any Tool
- 9. How to Set It Up
- 10. Your Bank Covers Less Than You Think
- 11. What to Spend and What to Skip
In short
- Pick the fraud problem first: Trustpair for vendor bank account fraud, Sift or SEON for e-commerce fraud, and skip Feedzai unless you are a bank or payment provider.
- Small online stores should start with Stripe Radar or Shopify's built-in fraud protection and add Sift or SEON only when dispute or fake-account numbers justify it.
- Run any new tool in parallel with your existing controls for four to six weeks before relying on it, since skipping this step leads teams to ignore alerts.
- Skip tools that need a dedicated implementation team, demand a 12-month minimum, or won't state their false positive rate, because your bank's detection protects the bank, not you.
Fraud doesn't scale with company size. A small business processing $2 million a year in vendor payments carries almost the same attack surface as one doing $20 million. The criminals targeting you don't care about your headcount. They care whether your controls have gaps.
For most of the last decade, serious fraud detection came from your bank, if you got it at all, and you had no view into why it flagged your biggest supplier three times in a month. That's changing. Purpose-built tools now exist for teams without a fraud analyst, and some of the best options are already sitting inside the payment platform you use.
This guide compares Sift, SEON and Trustpair, covers the SMB-native defaults (Stripe Radar and Shopify's built-in fraud protection), and shows how to set up whichever you pick without a security team.
Why Rule-Based Systems Are Losing Ground
Most small businesses start with rules. Block transactions over a certain amount. Flag international wires. Require dual approval for new vendors. These aren't bad controls. They're static, and fraud isn't.
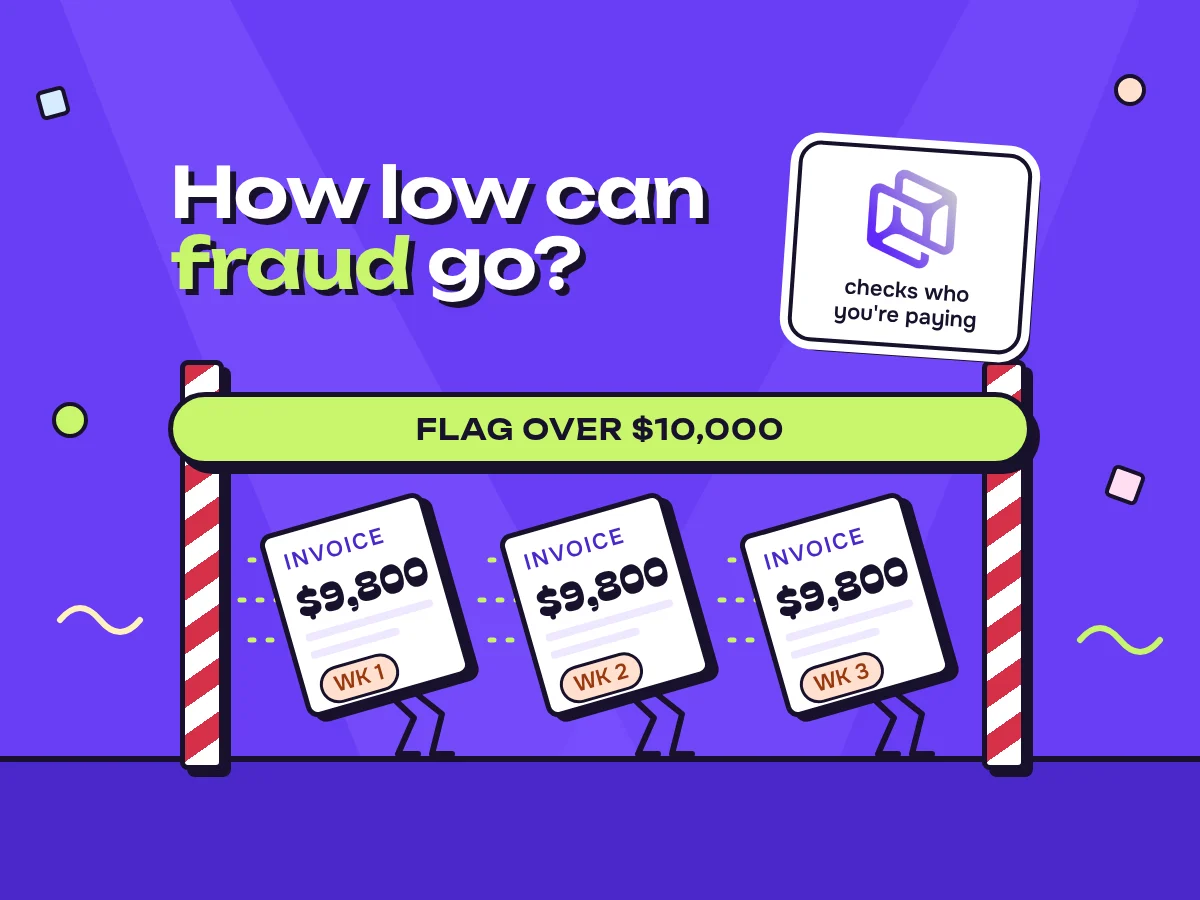
A rule that says flag anything over $10,000 does nothing when a fraudster sends three invoices at $9,800 each across three weeks. Attackers study approval workflows, mimic vendor email patterns and time their moves for when your finance person is on leave.
Machine learning tools work differently. They build a baseline of normal for your business, covering vendors, payment patterns and user behavior, then flag deviations. A vendor you've paid on the 15th of every month for two years suddenly asks for a bank account change and an urgent payment. A rule-based system might wave that through. A behavioral system should stop it.
The shift is from known-bad to unknown-anomalous. The system doesn't need to have seen the exact fraud pattern before. Keep your rules, though. Security vendors themselves recommend treating AI as one layer alongside other controls, not a replacement for them.
Which Fraud Problem Are You Solving?
These tools aren't interchangeable. Pick the problem first.
Vendor and payment fraud. Fake invoices, business email compromise, impersonators changing bank details. The core control is verifying that a vendor's bank account belongs to the company it claims to. Trustpair is built for this. Sift and SEON are not.
Account takeovers. Someone gets into your banking portal, ERP or customer accounts. Behavioral biometrics tools such as BioCatch study how a person interacts with a device. They matter most for digital-first businesses with lots of user accounts, and they mostly sell to larger organizations.
E-commerce payment fraud and chargebacks. If you sell online, this is your main exposure. Sift, SEON, Stripe Radar, Shopify's built-in protection, Signifyd and Kount all play here.
Transaction monitoring and AML. Feedzai and NICE Actimize work at bank-infrastructure level. A DevOpsSchool roundup lists high cost for smaller businesses and complex setup requiring AI expertise as Feedzai's drawbacks. Know that ceiling exists before you start shortlisting.
Comparison Table
Pricing details below are as of November 2026. Where a figure isn't published or couldn't be verified, the table says so. Get a written quote and ask about starting tier, minimum term and volume limits before you commit.
| Tool | Best for | Fraud type | SMB availability | Pricing model (Nov 2026) |
|---|---|---|---|---|
| Trustpair | B2B businesses paying suppliers | Vendor bank account validation, BEC | Built for finance teams, integrates with ERPs and payment systems | Contact vendor, no starting tier verified |
| Sift | Online stores with real chargeback exposure | Payment fraud, account takeover, promo abuse | Aimed at digital-native merchants | Contact vendor, no starting tier verified |
| SEON | Startups and small e-commerce or SaaS | Fake signups, trial abuse, new-customer payment fraud | Modular, a DevOpsSchool roundup cites transparent pricing and free trials | Published pricing and trial per that roundup, confirm current tiers on the vendor site |
| Stripe Radar | Businesses already on Stripe | Card payment fraud | Built into Stripe | Check Stripe's pricing page for current terms |
| Shopify fraud protection | Shopify merchants | Checkout and chargeback risk | Built into the platform | Check your Shopify plan for what's included |
| Feedzai | Banks and payment providers | Transaction monitoring, AML | Poor fit for small teams | Enterprise contracts |
Trustpair: Purpose-Built for Vendor Fraud
Vendor fraud is underrated as a small business threat. The attack is simple. Your finance person gets an email that looks like it's from a known supplier, explaining they've changed banks and asking you to update your records. Nobody hacked anything. Your team just did what the email asked.
Trustpair does one job. It checks that a vendor's bank account belongs to the declared company, integrates with ERPs and payment systems, and keeps validating after onboarding rather than only once. The vendor markets international coverage, so confirm that your supplier countries are supported before you sign.
It isn't glamorous. It does address one of the most common and most expensive fraud routes for companies that pay suppliers. If you move meaningful vendor payment volume, vendor account validation should be a baseline control. If you're sorting out the rest of your finance stack, our ranking of AI tools for accounting and tax professionals covers what sits upstream of those payments.
Sift: Built for E-Commerce Fraud
If you run an online store with real chargeback exposure, Sift deserves a serious look. It covers payment fraud, account takeovers, chargeback fraud and promotion abuse, and it scores behavior across the customer journey rather than only at checkout.
Sift's pitch is a shared network: patterns seen at other merchants inform scoring on yours. That's a real advantage for a small store with too little data to train anything itself. It's also something to test during a trial, since vendors rarely publish how much the network actually moves your results.
The tradeoff is fit. Sift is designed for digital-native businesses. If your exposure is B2B payments and supplier management, skip it and look at Trustpair.
SEON: The Accessible Option
SEON is modular, so you can start with specific capabilities instead of buying a full platform. Its approach centers on digital footprint enrichment and device fingerprinting. It takes signals like email addresses and phone numbers and cross-references them against online sources to profile new users.
For fake signups, trial abuse and new-customer payment fraud, it's easier to adopt than Feedzai or NICE Actimize. A DevOpsSchool roundup singles out SEON, along with Sumsub, for small businesses and startups because of transparent pricing, free trials and easy integration. Sumsub is the pick if your problem is identity verification and KYC rather than payment fraud.
The modular structure matters on cost. You aren't paying for AML tooling you'll never use.
The SMB-Native Defaults: Stripe Radar and Shopify
Before you buy anything, check what your payment stack already does. If you take cards through Stripe, Radar is part of that platform. Shopify merchants get fraud protection tied to checkout and chargebacks.
The case for starting here is simple. There's no integration project, the tool already sees every transaction, and you can measure it against your real dispute rate before spending anything extra. The limit is scope. These tools see activity on their own platform. They don't see your supplier invoices, your bank portal or your signups on other systems.
My view: for a small online store, use the built-in tool first and add Sift or SEON only when your dispute numbers or fake-account volume justify it. Merchants chasing chargeback prevention can also compare Signifyd and Kount, which the same roundup highlights for high approval rates and Shopify integrations.
Feedzai belongs on the shortlist only if you're a bank or payment provider. It's the tool your bank may already run on your behalf, and it isn't something you'd deploy yourself.
What a Small Business Needs From Any Tool
The enterprise market is built for teams with fraud analysts, data scientists and compliance departments. A 12-person operation needs a shorter checklist.
Real-time scoring. A flag 24 hours after the payment clears is a forensics tool, not prevention.
Readable reasons. Someone on your team has to decide whether to release or block a flagged payment, and that person is probably your accounts payable manager or CFO, not a fraud analyst. A flag saying the request came from an email domain registered 48 hours ago, for a bank account new to the vendor profile, outside business hours, is something you can act on. An anomaly score of 0.87 isn't. Vendors pitch explainability as a compliance feature. For you it's a usability feature.
Integrations that exist. A tool that doesn't connect to your ERP, payment processor or accounting software becomes a parallel workflow your team stops checking. Verify the integration is documented and live, not just an API on a roadmap. If the connection you need is missing, a workflow tool can sometimes bridge it, and our guide to open source Zapier alternatives by licence and self-hosting cost covers the self-hosted route.
A false positive rate. A system that blocks legitimate orders while catching fraud isn't protecting you. Ask every vendor for the number. If they can't give you one, that tells you something.
No AML module you won't use. Anti-money laundering tooling is built for regulated financial institutions. For a manufacturer or retailer it adds cost and complexity without covering your real risk.
How to Set It Up
Here's a rollout schedule I'd use. It's a suggested plan, not a vendor standard, and a very small team can compress it.
Weeks 1-2: Map your exposure. Write down your top three fraud risks. Vendor payments? Chargebacks? Account takeovers? That decides the tool category and stops you buying a platform that solves someone else's problem.
Weeks 3-4: Verify integrations. Check each shortlisted tool connects to what you run today, and that the integration is documented.
Weeks 5-8: Run in parallel. Keep your existing controls and run the new system alongside them for four to six weeks. Compare what each flags. This is how you calibrate sensitivity before you depend on it.
Weeks 9-10: Tune and hand off. Adjust thresholds using the false positive rate you saw. Document what happens when something is flagged, who reviews it and how fast.
The most common mistake is skipping the parallel phase. The team switches the tool on, gets false positives on legitimate transactions, decides it's broken and ignores the alerts. Then you're unprotected.
Feed the tool as much clean history as you can: vendor payment records, timing patterns, typical invoice amounts per supplier, standard approval workflows. Every behavioral system needs a baseline, and its quality decides whether you get signals or noise. Plan to keep reviewing performance and retraining or retuning after launch, because your own business changes too.
Tools that see the full chain, from vendor onboarding through invoice approval to payment, catch more than point solutions that only see the payment moment. Multi-step attacks are how sophisticated fraud works now.
Your Bank Covers Less Than You Think
Your bank's fraud detection protects the bank. If you authorize a wire to a fraudulent account because an email looked legitimate, the transfer is yours, and the bank's system has usually already approved it. That's the gap independent vendor-validation tools fill. Running your own validation layer isn't paranoid. It closes a hole in your existing controls.
If you sell online and field customer disputes by phone or chat, the cost of staffing that side is worth a look too. Our breakdown of what AI customer service agents cost small businesses shows how that spend compares.
What to Spend and What to Skip
Start with your highest-risk vector, not your full fraud surface. Vendor payment fraud first? Start with account validation. Chargebacks eating margin? Start with your platform's built-in tool, then step up. A broad platform bought to cover everything means paying for features you won't touch for 18 months.
Pay for tools that connect to your systems, explain their flags in plain language and let you calibrate against your own transactions. Skip anything that needs a dedicated implementation team, demands a 12-month minimum before you can validate it, or won't state its false positive rate.
This isn't legal or financial advice. Pricing and plan terms change, so confirm current figures with each vendor before you buy.
Fraud isn't getting easier to ignore. The tools available to small businesses are getting good, and relying on your bank alone is a harder position to defend each year.

Written by
Stanislav Vovchyk
Founder and editor of infobro.ai
I run infobro.ai: I decide what it covers and how tools are evaluated.
I research every tool from its documentation, pricing pages, product screenshots and public developer discussion, and say plainly what the evidence does and does not show.
More guides