How Independent Insurance Agents Use AI, Task by Task
Which AI jobs suit an independent agency, matched to tool type, risk and the human check. Includes dated survey data, notetaker and chatbot plans with training terms, AMS-native versus chatbot trade-offs, a policy checklist and a 30-day pilot.
 Stanislav VovchykAug 18, 202614 min readUpdated Nov 4, 2026
On this page · 11 sections
- 1. The adoption numbers disagree, and the gap tells you something
- 2. Task, tool type, risk and human check in one table
- 3. Lead intake and service calls: start small and log every conversation
- 4. Submissions, quoting and renewal comparison: AI prepares, the producer decides
- 5. Call notes: free plans have limits, and training terms vary
- 6. AMS-embedded AI versus a standalone chatbot
- 7. Marketing, retention and being found through AI search
- 8. What's oversold
- 9. Data safety and the AI policy
- 10. A 30-day pilot that ends with a decision
- 11. FAQ
In short
- Most independent agents use AI as one person with a chatbot: 45% of agencies use ChatGPT or another public chatbot, but only 8% have AI built into daily workflows.
- AI pays off in narrow jobs like call notes, submission prep and renewal comparison, but a licensed producer must check output and keep quotes, coverage advice and binding.
- Never paste client data into a plan that trains on your content; Otter.ai trains on it, Fathom does unless you opt out, while Fireflies.ai and Tactiq say they don't.
- Write an AI use policy, since 55% of agencies lack one, then run a 30-day pilot and drop any tool whose output takes as long to fix as to write.
Most independent agents use AI as one person with a chatbot, drafting emails, marketing copy and plain-language explanations. In the Big I Agents Council for Technology survey released on 19 February 2026, 45% of independent agencies named ChatGPT or another public chatbot as an AI tool they use, but only 8% said AI was built into their daily workflows. Notetakers, document extraction and AI features inside the agency management system (AMS) are starting to spread. AI pays off in narrow jobs where a licensed person checks the output. The hype is in carrier-grade underwriting tools and in single platforms that promise to run the whole agency.
The adoption numbers disagree, and the gap tells you something
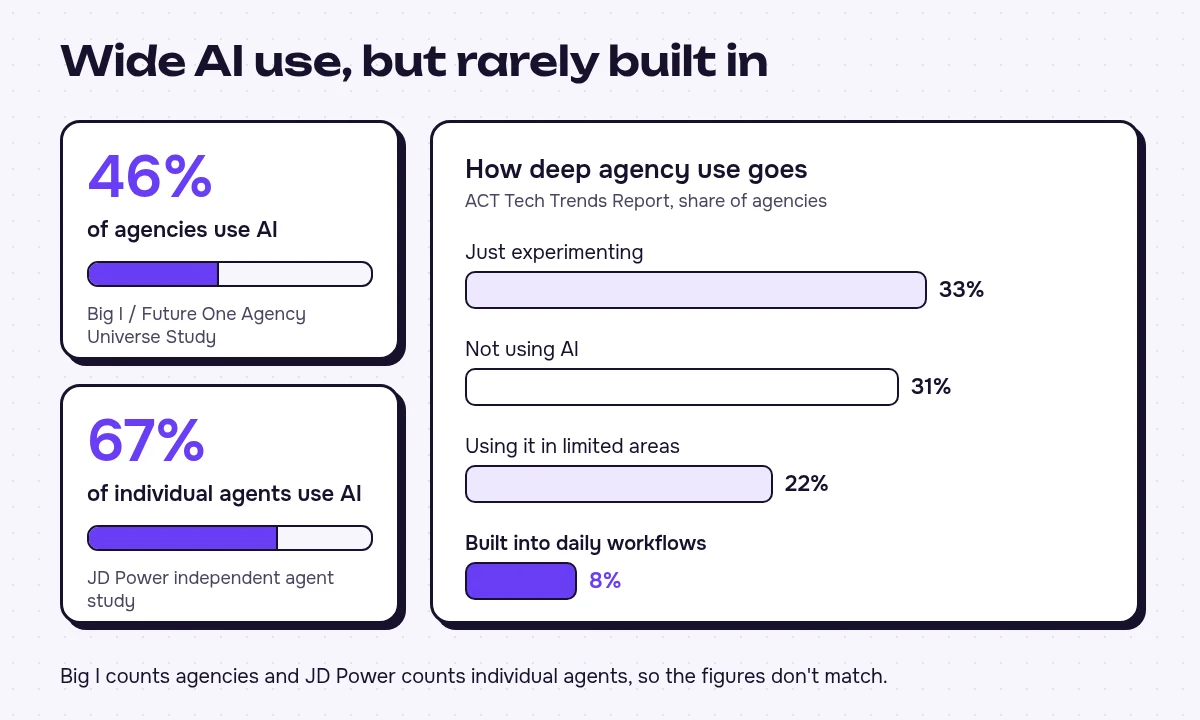
The Big I and Future One Agency Universe Study (2026) found that 46% of agencies use AI, up from 15% in 2024. The most common uses were marketing content (49%), coverage form analysis (43%) and contract reviews (35%). The top barriers were lack of knowledge about what AI can do (60%) and security and privacy (48%).
The ACT Tech Trends Report, an emailed survey of independent agency members, shows how shallow that use is: 33% of agencies said they were just experimenting, 31% weren't using AI, 22% used it in limited areas and 8% had it built into daily workflows.
JD Power's 2026 U.S. Independent Agent Satisfaction Study gives a higher figure. As reported by the trade site Beinsure, 67% of independent agents use AI: 73% of Gen Y and Gen Z agents against 34% of Baby Boomers. ChatGPT, Gemini and Copilot were the most common tools. One survey counts agencies and the other counts individual agents, so the numbers won't match. Read together, they say most AI use is one person with a chatbot, and only a small share of agencies has built it into the workflow.
Task, tool type, risk and human check in one table
| Task | Tool type | Main risk | Human check |
|---|---|---|---|
| Lead intake and after-hours calls | Chat or voice agent | Wrong coverage answers, recorded caller data | Review every conversation log; producer owns the quote |
| Submission prep from emails and PDFs | Document extraction, AMS-embedded AI | Misread limits or class codes | Compare extracted fields against the source before submitting |
| Renewal and policy comparison | Document comparison tool | Missed exclusion, confident wrong summary | Producer reads the endorsements the tool flags and the ones it doesn't |
| Call and meeting notes | Transcription notetaker | Client data used for vendor training: Fireflies.ai and Tactiq say they don't train on your content, Fathom does unless you opt out, Otter.ai does | Pick a tool whose terms fit; get consent where your state requires it |
| Client emails, plain-language explanations | General chatbot such as ChatGPT | Pasting PII into a plan that trains on your content | Redact first; a person edits and sends |
| Marketing and content | Marketing writing platform such as Copy.ai | Unreviewed claims about coverage | Compliance read before anything publishes |
| Retention and cross-sell flags | CRM scoring, AMS-embedded AI | Pushing products a client doesn't need | Account manager decides who gets contacted |
None of these tools is licensed to give advice. Quotes, coverage recommendations and binding stay with a producer.
Lead intake and service calls: start small and log every conversation
Chat and voice agents are still a minority tool: only 13% of agencies in the ACT report use chatbots or virtual assistants. Panelists at the Accelerate 2026 conference called voice AI for missed calls a high-value starting point, because it cuts voicemail friction and produces a transcript that can feed the CRM or AMS.
An intake agent should ask what a good producer asks in the first two minutes: personal or commercial, owned or rented, prior claims, desired effective date. The handoff matters more than the chat itself, because a lead that sits in a separate inbox gets ignored. The same goes for claims calls. Agents don't adjust claims, but they take the calls. A first-notice-of-loss intake that captures details and routes them to the carrier is a realistic use. Make sure it tells callers nothing about coverage and that a person calls back on any serious loss.
Most options are general support agents, not insurance products. Intercom Fin charges $0.99 per outcome with a 50-outcome monthly minimum, about $49.50 a month. Its privacy terms say it trains on customer content unless you opt out. Per-outcome pricing grows with volume: 1,000 outcomes in a busy renewal month would cost $990 at that rate. More options are in our customer support category.
Voice is harder. Vapi is a developer platform with $0.05 per minute hosting and $5 of free credits, and it trains on customer content. Unless someone at your agency writes code, I'd buy a finished receptionist product instead. Our guide to putting an AI voice agent on a business phone line covers what callers experience. Our breakdown of what AI customer service costs a small business covers when per-conversation pricing stops paying off.
Sample prompt for a follow-up a producer reviews and sends: Summarize this intake chat in five bullets: line of business, current carrier and expiration date, prior claims in the last five years, requested effective date, and open questions. Flag anything the prospect said that could affect eligibility. Do not recommend coverage.
Submissions, quoting and renewal comparison: AI prepares, the producer decides
The useful work here is clerical. AI reads an email thread, an ACORD form or a scanned application and fills in the submission fields, so a producer isn't retyping the same business name, revenue figure and loss history into three portals. Only 13% of agencies in the ACT report named document and data extraction tools, so this is still early. Treat extracted fields as a draft, and check class code, limits and effective date against the source. Before buying a standalone tool, ask your wholesaler, MGA or AMS vendor what AI they already include.
Sample prompt: From the attached loss runs, list each claim by date, line, paid amount and open or closed status in a table. Mark any field you can't read as UNREADABLE. Don't infer missing values.
Small commercial accounts are where this prep work pays off most. A Business Owner's Policy for a small company can need as much classification and documentation work as a larger account, for a much smaller premium, and some carriers now take part of that work on themselves. MGT Insurance, a commercial property and casualty insurer that writes through independent agents, pulls third-party data into the application and checks underwriting appetite before the agent builds a full submission. Its assistant, Aimee, tells the agent whether a business is likely to fit MGT's guidelines. Straightforward submissions go through an automated flow, and questions about classification or limits go to an underwriter.
Renewal comparison follows the same pattern. You upload the expiring policy and the incoming quote, and the tool lists differences in exclusions, limits and endorsements in plain language. That list becomes the starting point for the coverage conversation. A junior account manager can run the comparison while the producer reviews the flagged items. Coverage form analysis (43%) and contract reviews (35%) already rank second and third among agency uses in the Big I study. The risk is a confident summary that skips an exclusion, so the producer still reads the policy. Specific prompts produce checkable output:
Sample prompt: Compare the expiring and renewal commercial general liability policies. List every change in limits, deductibles, exclusions and endorsements. Quote the policy language for each change and give the page number.
Call notes: free plans have limits, and training terms vary
Transcription is the pilot I'd run first, because it doesn't touch a quote. It does put client voices on a vendor's servers, so the training terms matter more than the price.
| Notetaker | Cheapest paid plan | Free plan limit | Trains on your content |
|---|---|---|---|
| Otter.ai | $8.33/user/mo billed annually | 300 minutes a month, 30 minutes max per conversation | Yes |
| Fireflies.ai | $10/seat/mo billed annually | 400 minutes of team storage, limited AI summaries | No |
| Fathom | $15/mo (Team, billed annually) | Unlimited recordings and transcripts | Yes, opt-out available |
Otter's free plan caps each conversation at 30 minutes, so longer calls get cut off. Tactiq also says it doesn't train on your content, and its free plan covers 10 transcripts a month. Fireflies and Fathom both list HIPAA among their compliance badges. Even so, get the business associate terms in writing before any health or Medicare conversation goes through them. If you'd rather keep audio on your own machine, see our open-source Otter alternatives.
AMS-embedded AI versus a standalone chatbot
Applied Systems' May 2026 blog says AI inside its AMS drafts emails, summarizes accounts before renewals and flags cross-sell gaps. It argues that the most useful agent AI is built into the tools agents already use and trained on insurance data. That is a vendor making the case for its own product, so weigh it accordingly. EZLynx, another AMS vendor, drew the line this way in a May 2026 webinar: general AI helps you shape communication and get organized, while insurance-specific AI inside your systems works with real account activity and follow-ups instead of whatever you type in.
Vertafore is the other AMS most independent agencies weigh. Put the questions below to your Vertafore rep, as you would to Applied or any other AMS vendor.
| AMS-embedded AI | Standalone chatbot | |
|---|---|---|
| What it sees | Account records, activity and follow-ups already in your AMS | Only what someone types or pastes in |
| Where data is processed | Inside the AMS vendor's environment, under your existing contract | On the chatbot vendor's servers, under that plan's terms |
| Extra cost | Depends on whether your subscription includes the feature | ChatGPT runs from Free at $0 to Pro from $100 a month |
| Suits | Agencies whose data is clean and complete in the AMS | Drafting and explaining where no client data is needed, and solo producers |
Questions to ask an AMS vendor:
- Which AI features does our current subscription include, and which cost extra?
- Where is our data processed and stored, and which outside AI providers handle it?
- Is our client data used to train your models or a partner's, and is that on or off by default?
- Does the AI write results back to the client record, or does someone copy them over?
- What does a staff member see before AI output reaches a client or carrier?
Workflow tools connect the systems an AMS doesn't. Zapier gives you 100 tasks a month on its free plan, two-step Zaps only, then Professional from $19.99 a month, and it doesn't train on customer content. Make starts at $9 a month billed annually (Core, 10,000 credits). n8n has a free self-hosted Community Edition and also says it doesn't train on customer content, which suits an agency with a technical person. For options that run on your own server, see our open-source Zapier alternatives.
Marketing, retention and being found through AI search
Marketing is the most common use in the Big I study (49%) and the easiest to get wrong. A drafted blog post about flood coverage is fine. A published sentence stating what a policy covers needs compliance review. Besides ChatGPT, the names that come up for this work are Claude and Jasper for drafting, Grammarly for editing and Canva for social graphics and flyers. Whichever you use, the redaction rule below applies.
Vague requests get generic posts. Compare "write a post about umbrella insurance" with this:
Sample prompt: Write a 400-word post for homeowners in [county] explaining when an umbrella policy makes sense. Use plain language, no coverage promises, and end with an invitation to book a policy review. Flag any sentence that describes what a policy covers so we can check it.
Retention scoring and renewal outreach drafts suit personal lines books with many small accounts, where clients drift away without saying anything. The risk is a cross-sell push that doesn't fit the client, so an account manager picks who gets contacted.
The newer use case is how consumers find you. JD Power's U.S. AI Insurance Experience Study (press release, 27 August 2026) found that 29% of auto and home insureds have used AI to research, service an account or shop for a policy. Among customers who used AI-assisted tools to research products and coverage, 42% bought a policy based on that research. Your website and Google business profile feed those answers. Write plain-language pages on the questions clients ask, such as what an umbrella policy covers, and state your carriers and licensed states clearly.
What's oversold
Carrier-grade underwriting platforms. The NAIC's examples of AI in underwriting and pricing are insurer-side work built on insurer claims data. An independent agency has nothing comparable to feed such a model, so ask any vendor pitching one who its customers are.
One platform for every job. In the ACT report, 16% of agencies named too many disconnected systems as their top tech challenge. A vendor claiming to cover intake, quoting, review and retention in one product is often selling a roadmap. Pick one tool per job and make sure each writes back to your AMS.
Hours-saved and ROI claims. The surveys above measure adoption, not time saved. Figures such as Sonant's "8X ROI in 30 days" for O'Connor Insurance appear on Sonant's own site, about its own AI receptionist. Measure your own baseline before you believe any number.
Data safety and the AI policy
The ACT report found that 55% of agencies have no written AI use policy, 23% have one in development and 13% have a formal one. The top concerns were data privacy or compliance risk (24%) and inaccurate outputs (22%). In the release, ACT's Connors said agents "aren't worried about the price of AI, they're worried about the cost of getting it wrong."
Is it safe to paste client information into ChatGPT or Claude? Not into a plan that trains on your content. ChatGPT (Free $0, Go $8 a month in the US, Plus $20, Pro from $100) is listed in our catalogue as training on customer content, so check the setting on the exact plan your staff use. For whichever tool and plan you pick, find the clause in the vendor's privacy policy or data-use terms that says whether your inputs and outputs are used to train or improve models. Note whether that is off by default for your plan or needs an opt-out, and how long conversations are kept. If the clause doesn't clearly exclude training, keep client data out.
A one-page policy should cover:
- Never enter: client names with policy numbers, Social Security numbers, dates of birth, health details, payment data or carrier portal credentials.
- Redact first: strip identifiers from documents before upload.
- Approved tools: a short named list, with the plan tier each person uses.
- Output is a draft: a licensed person reviews anything that reaches a client or carrier, and compliance signs off on published marketing.
- Recording consent: state rules on call recording apply to AI notetakers.
- Incident step: who to tell when something sensitive goes into the wrong tool.
- E&O: ask your E&O carrier how it views AI use before you scale.
You don't have to start from a blank page. Big I's technology hub at independentagent.com/technology includes a sample AI acceptable use policy, Agency AI Labs training, a case study library of agency examples and ACT's resources for evaluating technology vendors. On the regulatory side, the NAIC has a model bulletin on the use of AI by insurers. It is aimed at carriers, not agencies, and adoption differs by state, so ask your state insurance department what applies to you.
A 30-day pilot that ends with a decision
Choose the first workflow to suit your agency:
- Solo producers: a notetaker and a drafting assistant cover most of the value. Intake agents and workflow builders can wait.
- Health and Medicare brokers: keep client conversations out of consumer chat plans entirely. PHI needs a vendor that will sign the right terms.
- Agencies with weak process documentation: standardize the process first. The Accelerate 2026 panel made the same point about consistent data entry, because extraction and routing tools amplify messy inputs.
- Commercial teams of 10 or more: start with policy comparison and AMS-embedded features, where the document volume is.
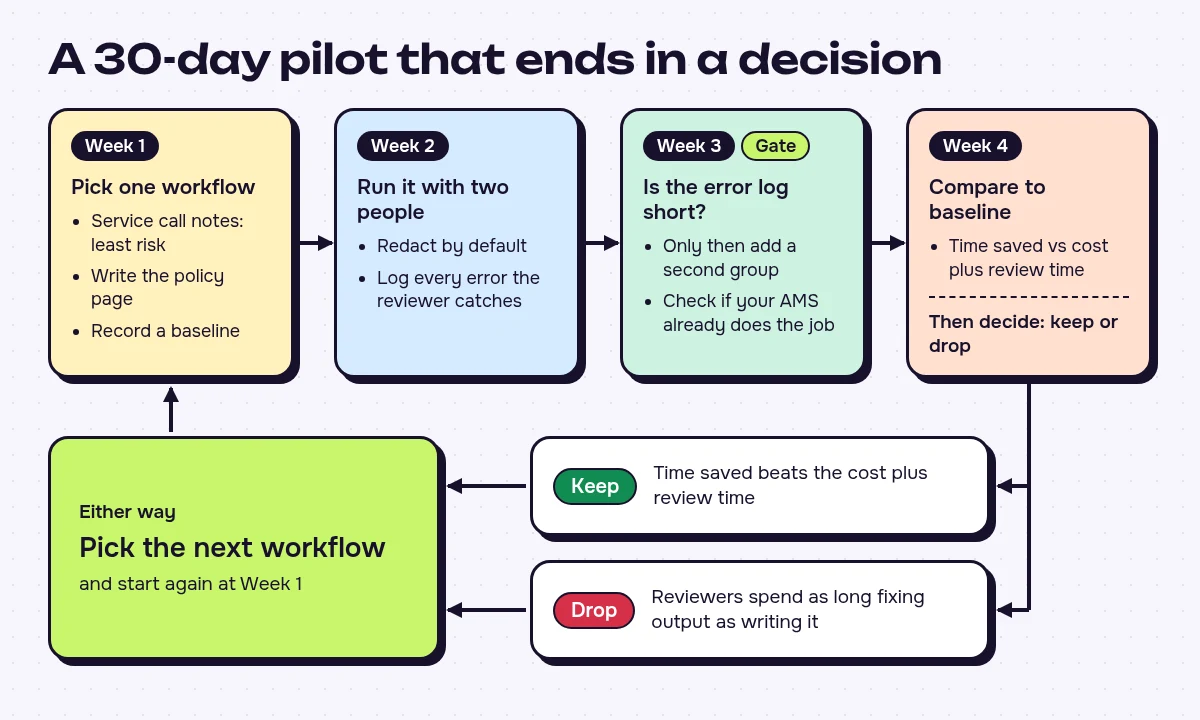
Week 1: Pick one workflow. Notes on service calls carry the least risk. Write the policy page above. Record a baseline: minutes per call write-up, or hours to first response on web leads.
Week 2: Run it with two people. Redact by default. Log every error the reviewer catches.
Week 3: Add a second group only if the error log is short. Check whether your AMS already has features that do the same job.
Week 4: Compare to baseline. Keep the tool if the time saved beats the cost plus review time. Drop it if reviewers spend as long fixing output as writing it themselves. Then pick the next workflow.
FAQ
Will AI replace insurance agents or underwriters? I don't see it going that way. The NAIC describes insurer models that automate, augment or support human decisions depending on the use, and Smart Choice says carriers keep people involved in important decisions. Agents still hold the client relationship, the coverage advice and the binding authority. In the ACT survey, 17% of agencies named losing the human touch as a top concern.
How is AI used across the insurance industry? According to the NAIC, property and casualty insurers use AI for renewal evaluations and inspections in underwriting, risk scoring in pricing, and accident image analysis, settlement estimates and fraud detection in claims. Smart Choice's August 2026 guide says agents are most likely to notice quicker responses, better-organized requests for missing information and more timely status updates. It also warns against promising clients a turnaround the carrier hasn't committed to.
Which tasks save the most time, and what hasn't worked? No independent source measures time saved by task. The Big I study shows where agencies put AI first: marketing content, coverage form analysis and contract reviews. QueryNow, a firm that sells AI agents to agencies, argues the bigger payoff is in service and renewal work. As for what goes wrong, EZLynx's webinar names the common mistakes: client and policy details dropped into public tools, and AI responses sent out without a second look. ACT's Connors points to disconnected systems and limited automation as the reason many agencies struggle to get past experimenting.
How do I start with no technical background? Pick a notetaker or a drafting assistant, since neither needs code, and follow the four-week plan above. Leave developer platforms such as Vapi or self-hosted n8n until someone on staff can run them. Big I's Agency AI Labs, its case study library and the ACT evaluation resources at independentagent.com/technology are free places to learn from other agencies.



Written by
Stanislav Vovchyk
Founder and editor of infobro.ai
I run infobro.ai: I decide what it covers and how tools are evaluated.
I research every tool from its documentation, pricing pages, product screenshots and public developer discussion, and say plainly what the evidence does and does not show.
More guides